Thinking the insurance adjuster is on your side
Their adjuster is paid by the insurance company. Learn who each adjuster really works for.
Hey {{first_name}}, you're in.
How to level the playing field and get a fair settlement without out-of-pocket stress.
We also sent a copy to your email. Don't see it in 5 minutes? Check your spam or promotions folder.
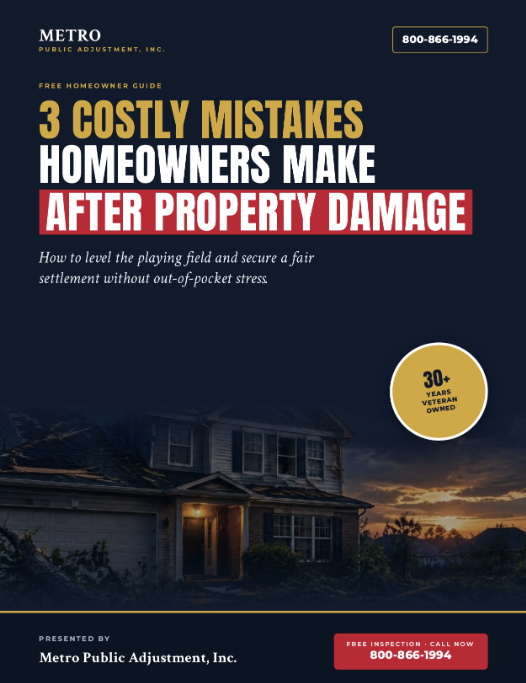
YOUR FREE HOMEOWNER'S GUIDE
Most people find out about these after the check is cashed. You get to read them first.
Their adjuster is paid by the insurance company. Learn who each adjuster really works for.
That first check is often just a starting offer. Learn what to know before you sign or deposit it.
If it isn't documented, it didn't happen. Learn what proof the insurance company wants to see.
Contractor's estimate for a new roof
First insurance check
Left for the owner to pay
Example from the guide. Every claim is different.
Lots of owners think that first check is all they get. So they pay the rest out of pocket or hire a cheap contractor. You have the right to question the number, send in more damage as it's found, and ask for a fair settlement based on real local prices.
When you have damage, the insurance company sends an adjuster who works for them. That person is trained to keep payouts low. The burden of proof is on you. Policies are full of forms and fine print most people never read. So owners who are stressed and worn out settle for less than they're owed.
Works for the insurance company.
→ Works for the insurerHired by the insurance company.
→ Works for the insurerHired by you. Licensed. Works only for you.
→ Works for youA public adjuster on your side levels the playing field.
A licensed claims rep comes to your property with pro tools. Many owners have damage they never knew was covered, like water stains, carpet damage and hidden leaks.
Metro files the claim, goes to every meeting with the insurance company's adjuster, and does the talking for you.
Already took a payout without help? Metro will review it and tell you if it may be worth challenging.
A pro reads your policy and finds the gaps before a loss, not after. It's too late to find a gap after the damage is done.
For homeowners and business owners. Water, fire, storm and roof damage. Denied claims and lowball offers.
Call 800-866-1994 or book online. It takes two minutes.
A licensed pro inspects the damage and reviews your policy. No cost. No obligation.
Paperwork, proof, meetings and negotiations. All of it.
Metro's fee is a percentage of the settlement. If your claim doesn't pay, you don't pay them.
In 1985, Steven J. McCaffrey's parents had water damage at their home. Their insurance company denied the claim. A public adjuster read their policy, explained their options, and charged nothing for the advice. He only got paid if the claim paid. Steven never forgot it. Today, as President of Metro Public Adjustment, his mission is simple: to protect and educate the policyholder.
Metro Can Make The Difference.
[PASTE ROB OWENS QUOTE FROM METROPA.COM]
Rob Owens
[PASTE DEBORAH FROST QUOTE FROM METROPA.COM]
Deborah Frost
[PASTE KAREN JONES-EDNEY QUOTE FROM METROPA.COM]
Karen Jones-Edney
Reading the guide is step one. Step two is having a licensed pro look at your damage. Time matters, because policies have deadlines for filing and reopening claims.
Or email info@metropa.com